 Money in One Chart
bad month
In a bad month, cutting the wrong thing first can cost you for years.
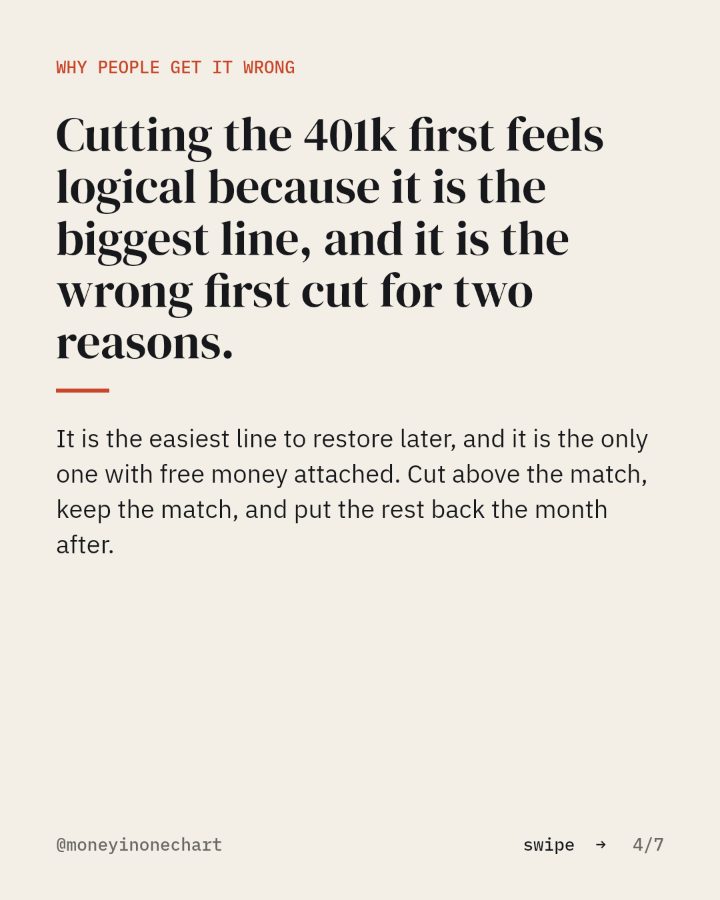
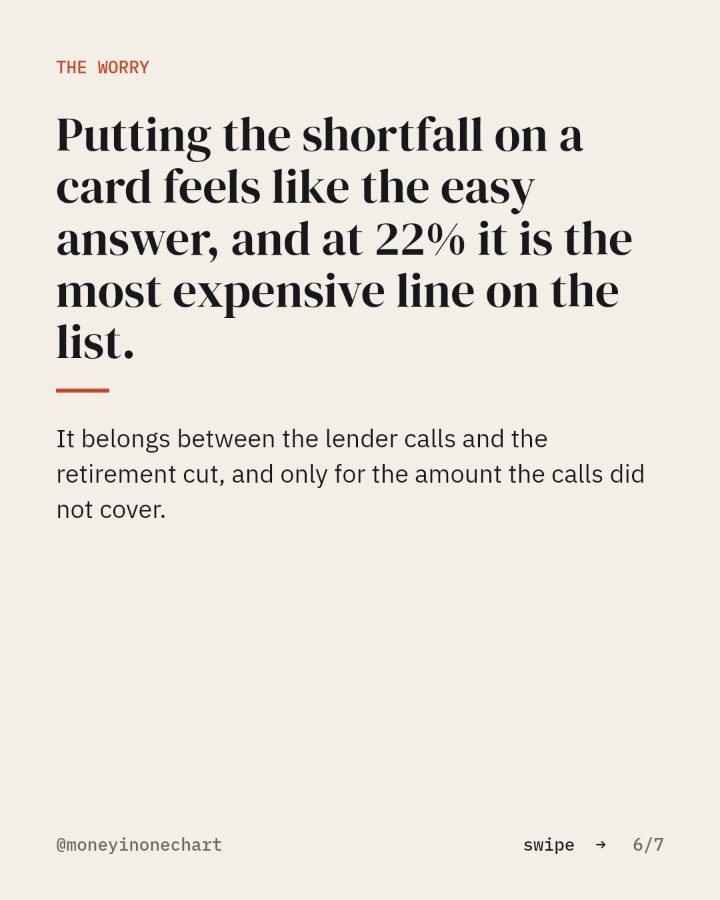
Subscriptions first, then variable spending, then a call to every lender, then retirement above the match. A missed payment costs more than anything on that list.
You asked for the bad-month checklist. It is below, as the slides from the post, then the one move, then the tool the chart points at.
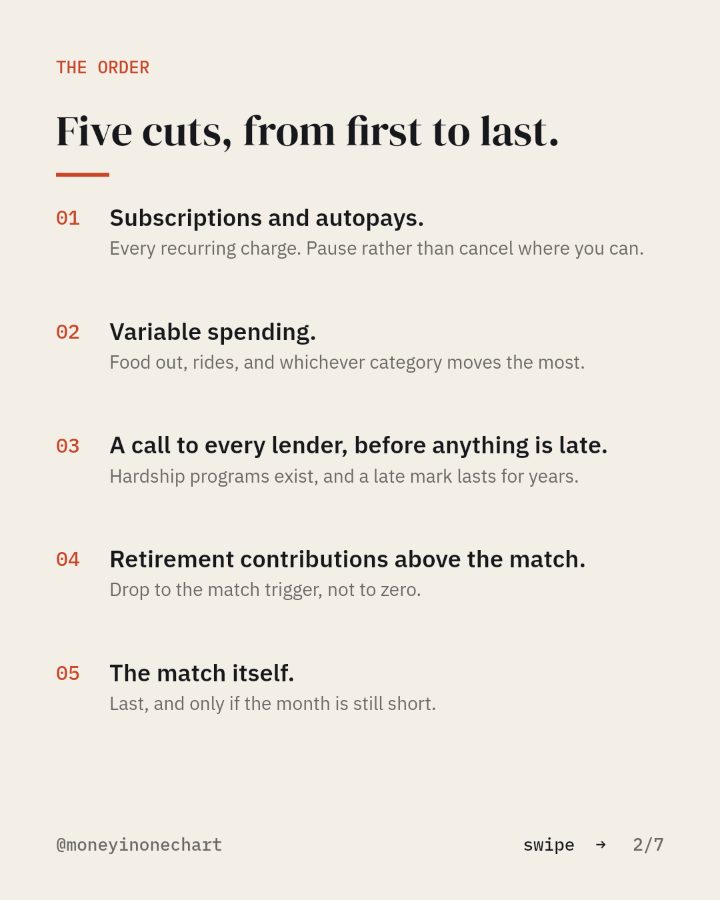
Five cuts, from first to last.
- 01Subscriptions and autopays.Every recurring charge. Pause rather than cancel where you can.
- 02Variable spending.Food out, rides, and whichever category moves the most.
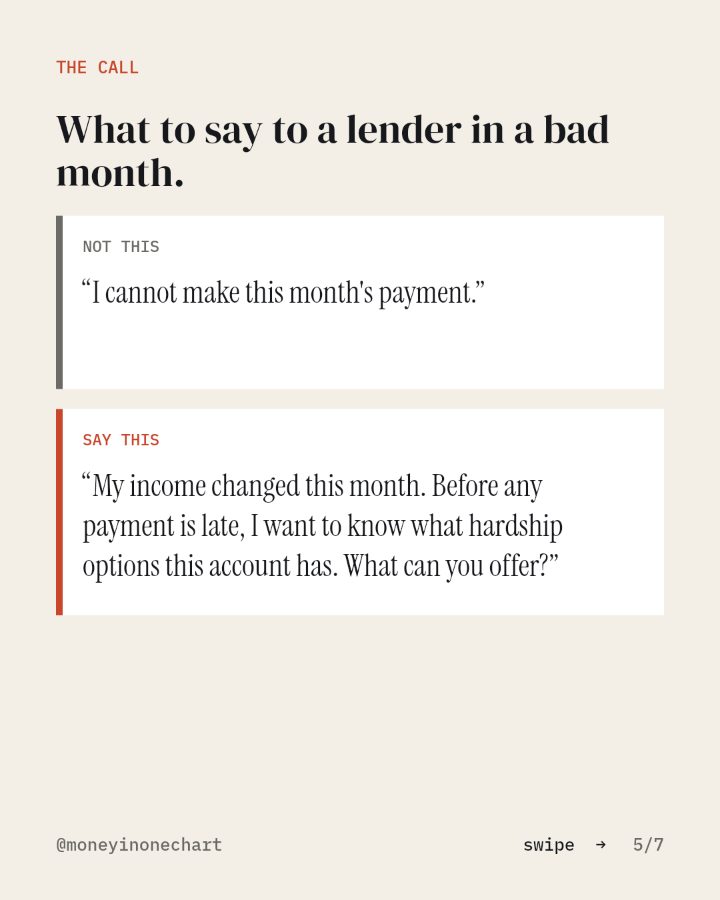
- 03A call to every lender, before anything is late.Hardship programs exist, and a late mark lasts for years.
- 04Retirement contributions above the match.Drop to the match trigger, not to zero.
- 05The match itself.Last, and only if the month is still short.
The tool this chart points at
Free credit monitoring
Know the score before a lender does. Free, no card required.
Open it