 Money in One Chart
money at work
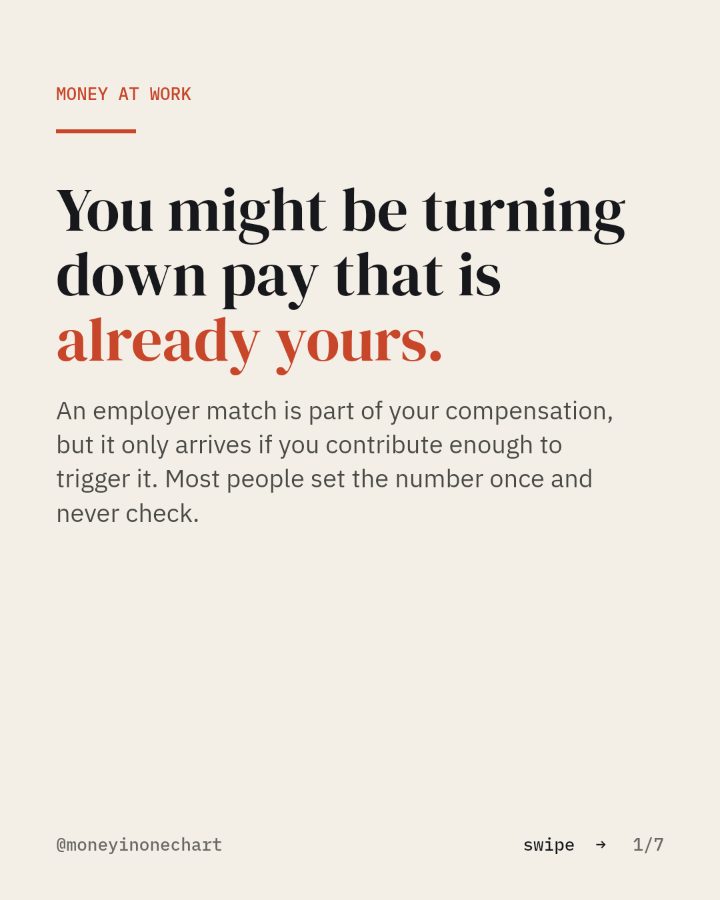
You might be turning down pay that is already yours.
An employer match is part of your compensation, but it only arrives if you contribute enough to trigger it. Most people set the number once and never check.
You asked for the one-line question to send HR. It is below, as the slides from the post, then the one move, then the tool the chart points at.
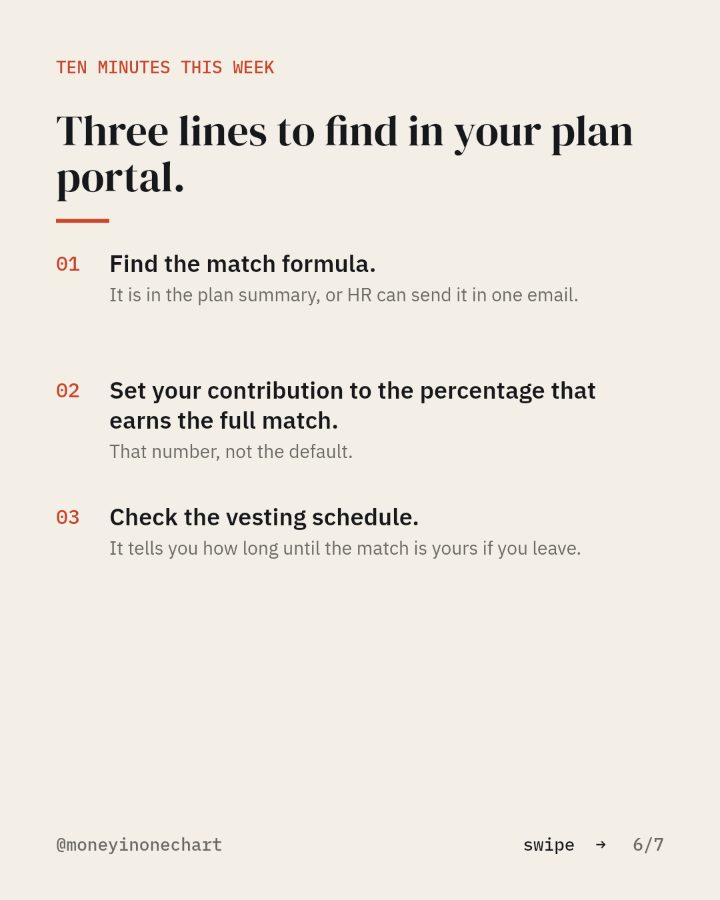
Three lines to find in your plan portal.
- 01Find the match formula.It is in the plan summary, or HR can send it in one email.
- 02Set your contribution to the percentage that earns the full match.That number, not the default.
- 03Check the vesting schedule.It tells you how long until the match is yours if you leave.
The tool this chart points at
A low-fee brokerage
For the IRA, the index fund and the rollover. Broad index funds with expense ratios under 0.1%.
Open itThis link may pay Money in One Chart a referral fee if you open an account. Your price does not change. How that works.
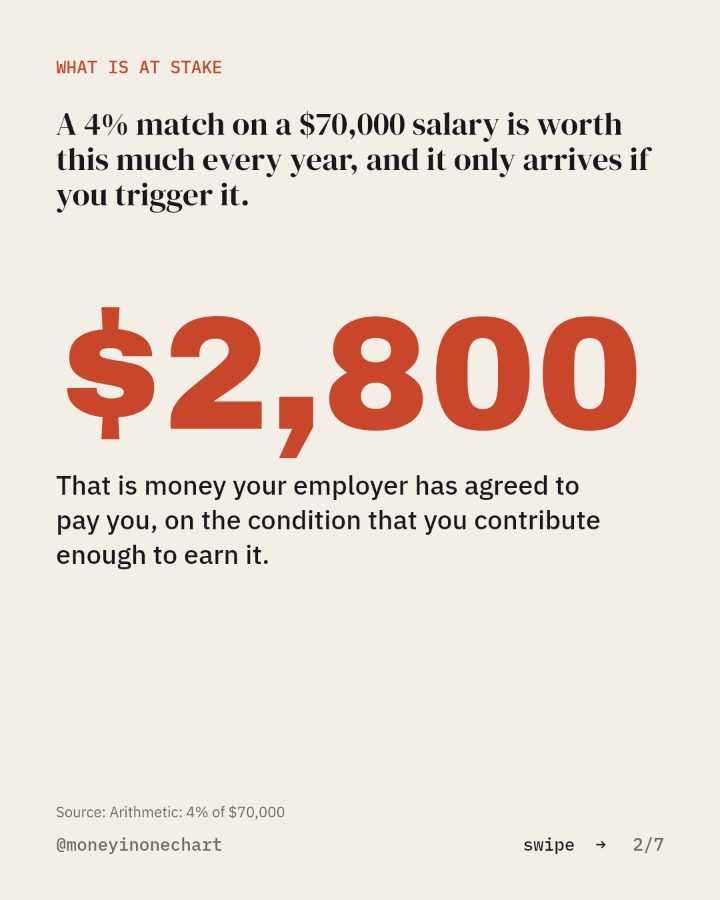
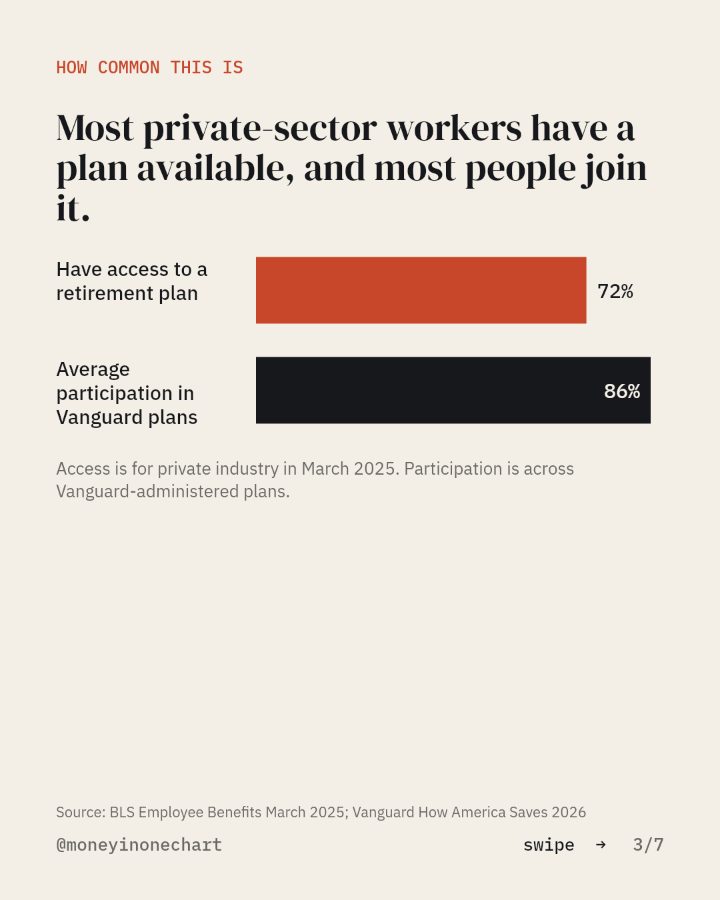
Sources: Arithmetic: 4% of $70,000; BLS Employee Benefits March 2025; Vanguard How America Saves 2026.