 Money in One Chart
where money goes
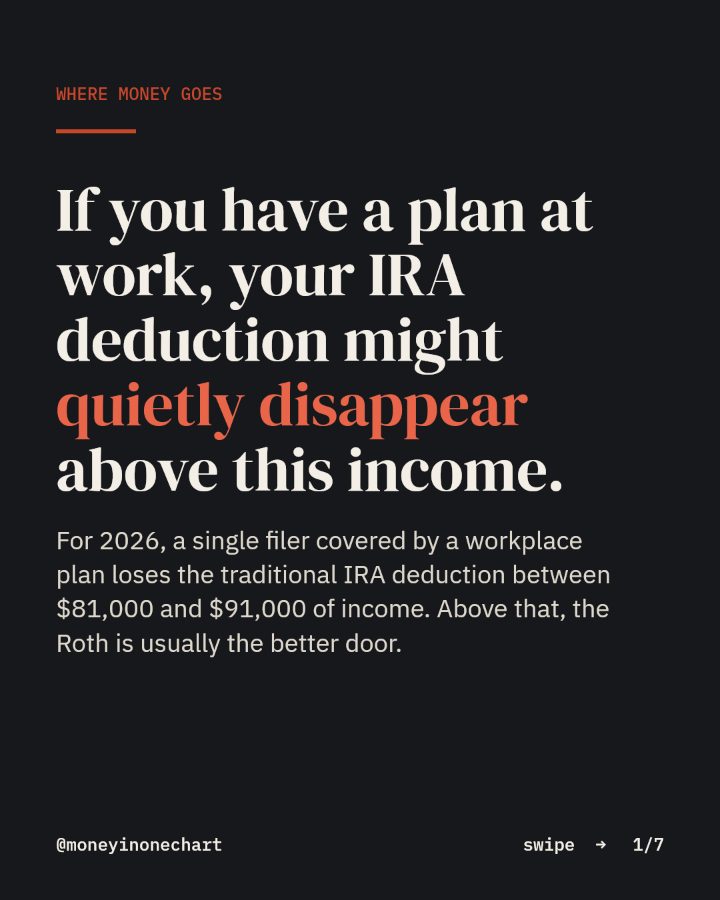
If you have a plan at work, your IRA deduction might quietly disappear above this income.
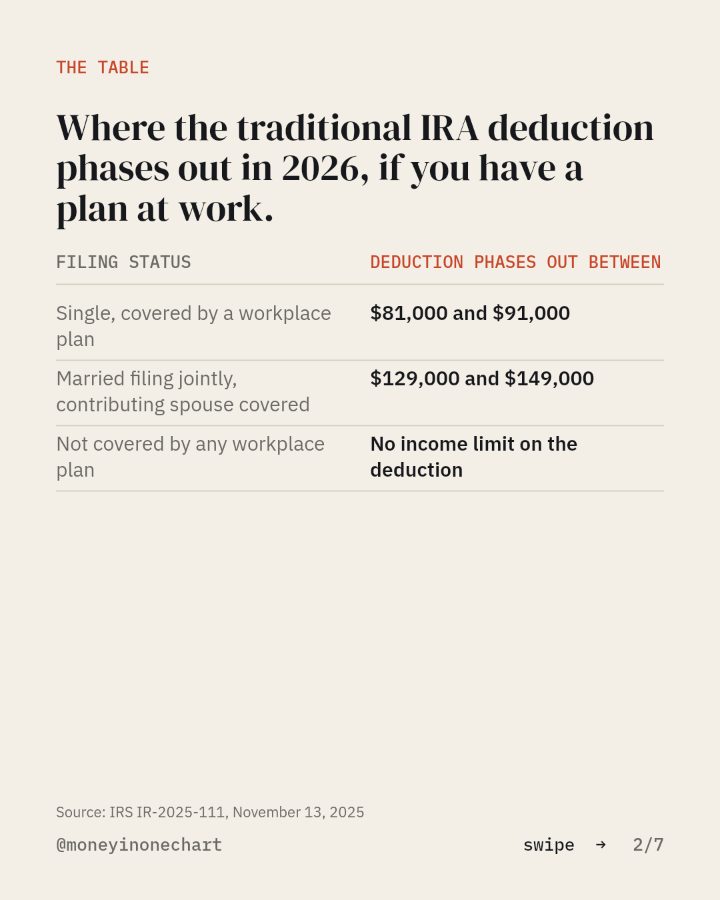
For 2026, a single filer covered by a workplace plan loses the traditional IRA deduction between $81,000 and $91,000 of income. Above that, the Roth is usually the better door.
You asked for the IRA door decision card. It is below, as the slides from the post, then the one move, then the tool the chart points at.
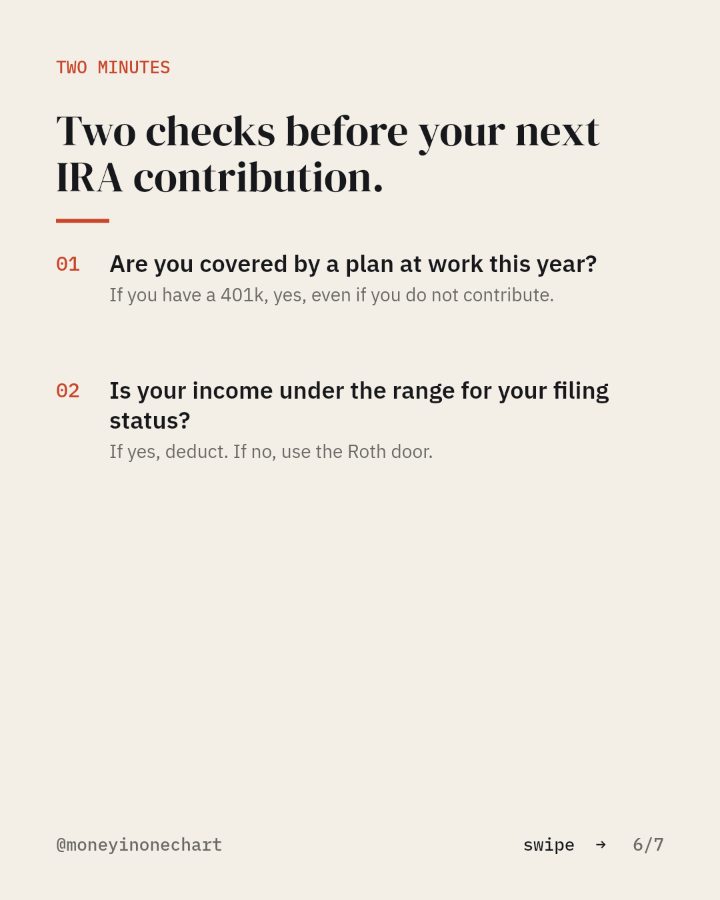
Two checks before your next IRA contribution.
- 01Are you covered by a plan at work this year?If you have a 401k, yes, even if you do not contribute.
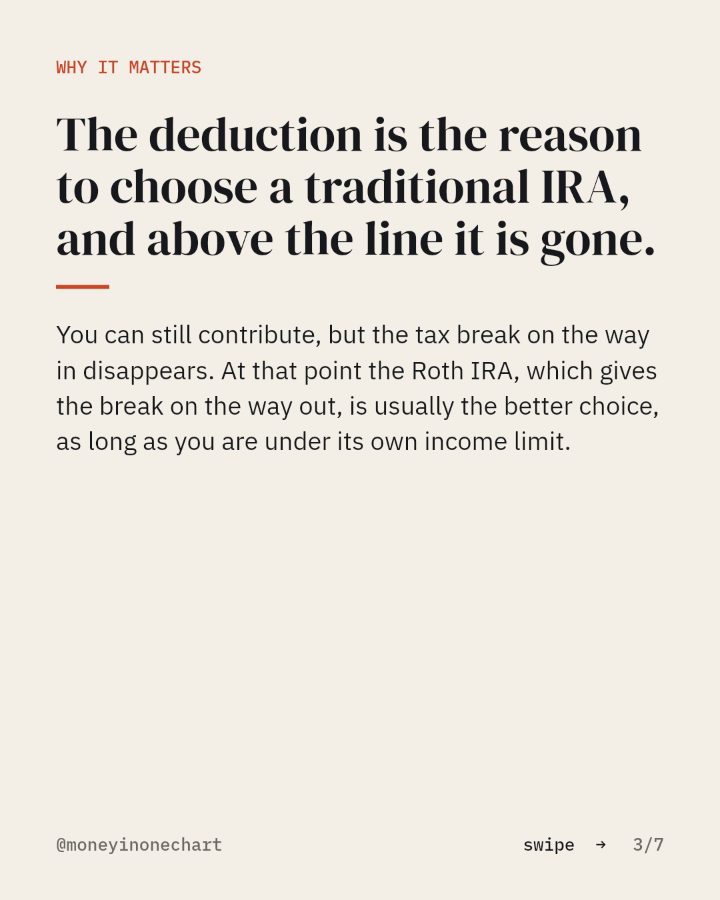
- 02Is your income under the range for your filing status?If yes, deduct. If no, use the Roth door.
The tool this chart points at
A low-fee brokerage
For the IRA, the index fund and the rollover. Broad index funds with expense ratios under 0.1%.
Open itThis link may pay Money in One Chart a referral fee if you open an account. Your price does not change. How that works.
Sources: IRS IR-2025-111, November 13, 2025.